Key Takeaways
- Provisional tax submissions (IRP6) occur twice per fiscal year, requiring accurate taxable income projections to avert Section 89quat penalties.
- Monthly EMP201 payroll filings for PAYE, UIF, and SDL must clear the SARS eFiling system on or before the 7th of every month.
- Bi-monthly VAT201 electronic returns demand reconciliation of both output supplies and valid tax invoices for all deductible input claims.
01Navigating the Annual SARS Filing Calendar and Corporate Returns
Small corporate entities registered as private companies (Pty Ltd) in South Africa face a rigorous statutory schedule overseen by the South African Revenue Service (SARS). Corporate Income Tax (CIT) return submissions (ITR14) fall due exactly twelve months following the end of the enterprise's financial year. For businesses whose financial calendar closes at the end of February, the annual return must be filed and accepted on eFiling before the close of February the following year. Maintaining spotless corporate compliance is not merely an administrative exercise; it directly governs your enterprise's Tax Compliance Status (TCS), which commercial clients, municipal tenders, and institutional supply chains verify before awarding work or releasing disbursements.
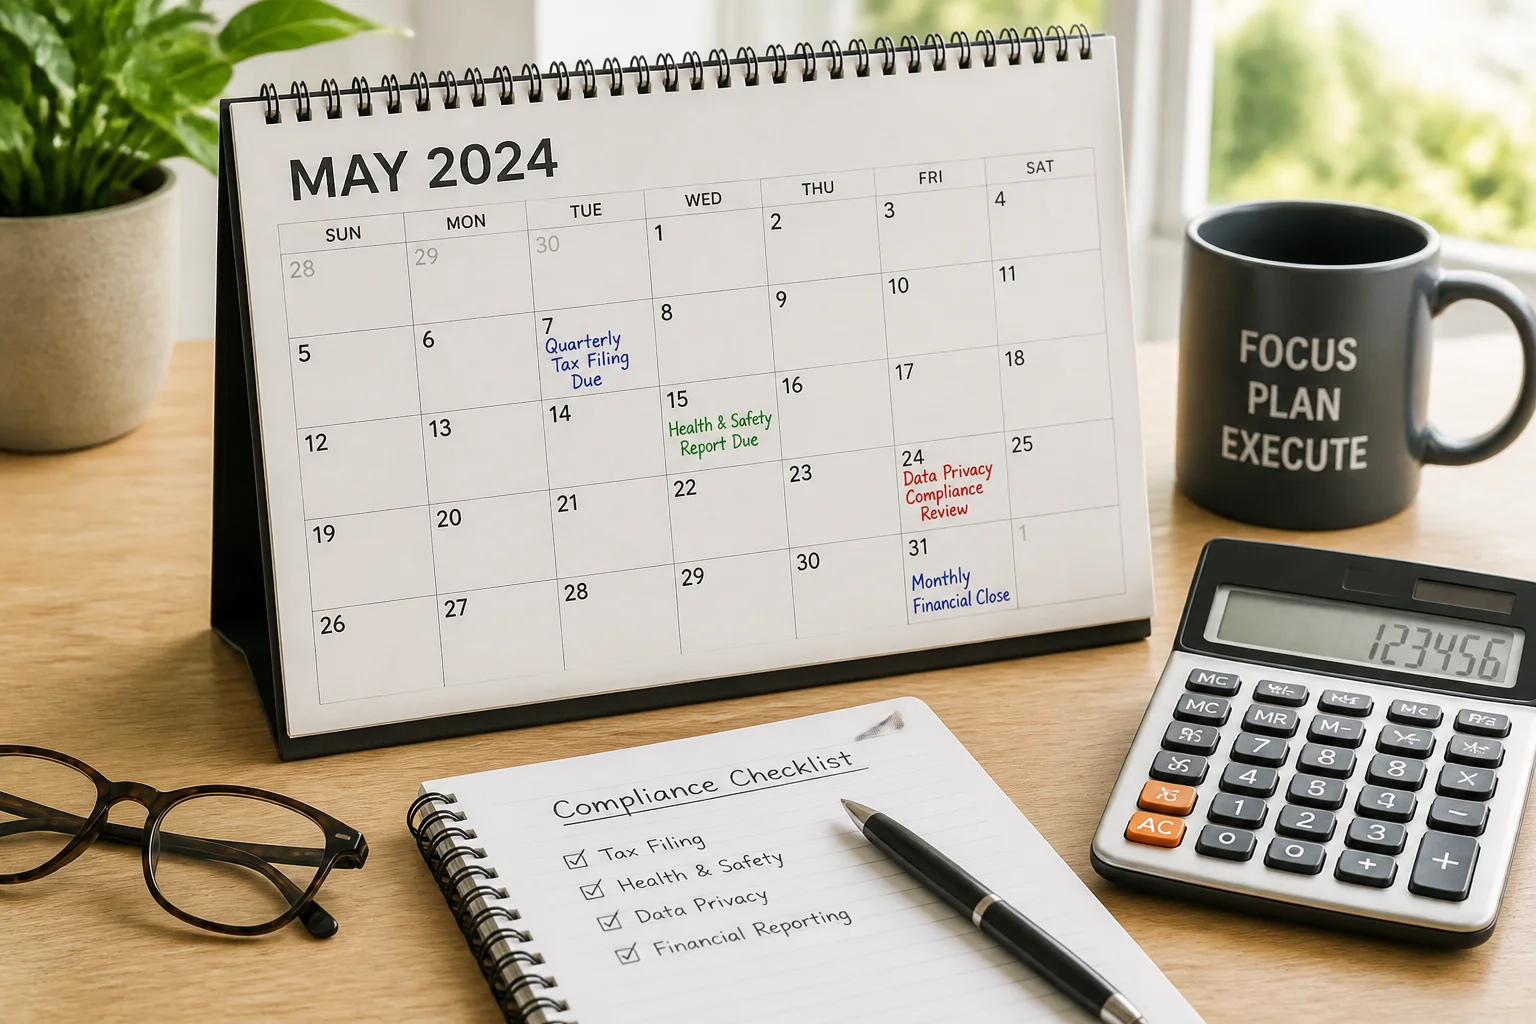
Administrative neglect often creates compounding liabilities. SARS automatically issues administrative non-compliance penalties for every month an outstanding annual or provisional return remains unfiled. These recurring penalties accrue regardless of whether the business generated net profit or experienced an operational deficit. Establishing an internal compliance tracker and aligning your general ledger closing procedures 60 days before the statutory deadline guarantees sufficient time for comprehensive balance sheet reconciliations, asset depreciation schedules, and wear-and-tear allowance calculations under Section 11(e) of the Income Tax Act.
Regulatory & Operational Facts
- Annual ITR14 Filing Window
- Within 12 months after the close of the financial year
- Provisional Tax Cycles (IRP6)
- Period 1 due at 6 months; Period 2 due at year-end
- Monthly EMP201 Cut-off
- 7th day of the following calendar month
- VAT Registration Threshold
- Compulsory above R1 million taxable supplies in 12 months
02Managing Provisional Tax Calculations and Estimation Safeguards
Provisional tax is not a separate form of taxation, but rather an advance payment mechanism designed to distribute an enterprise's annual liability across the trading year. All companies incorporated in South Africa are provisional taxpayers by statutory definition. The first provisional return (IRP6) must be submitted within six months of the financial year's start—typically August 31 for standard February-year-end enterprises. This submission reflects an estimation of total taxable profit for the entire fiscal period, with half of the projected liability payable upon submission.
- Utilize the Basic Amount benchmark prudently: if taxable turnover exceeds R1 million, the final second-period estimate must reach at least 80% of actual taxable income or face severe 20% underestimation penalties under Paragraph 20 of the Fourth Schedule.
- Factor seasonality and cyclical cash flow trends into mid-year forecasting, particularly when peak trading occurs during coastal holiday rushes or fourth-quarter wholesale surges.
- Submit voluntary third-period top-up payments (due six months after year-end, typically September 30) if actual audited taxable profit significantly outpaces the initial February estimate, thereby mitigating Section 89quat interest charges.
Financial leaders must maintain documented working papers supporting every submitted IRP6 estimate. When economic shocks or supply chain disruptions compress operating margins, SARS may demand proof that your revised revenue projections were calculated with realistic commercial diligence rather than an arbitrary attempt to preserve working cash reserves.
03Payroll Withholding and Value Added Tax Governance
Operational compliance extends into weekly and monthly employer obligations. Any enterprise with qualifying staff must deduct Pay-As-You-Earn (PAYE) according to statutory tax tables, along with 1% employee and 1% employer Unemployment Insurance Fund (UIF) contributions, plus the Skills Development Levy (SDL) where annual payroll exceeds R500,000. These deductions are aggregated on the monthly EMP201 declaration, which must be declared and settled by the 7th day of the succeeding month. If the 7th falls on a weekend or public holiday, clearance must occur on the preceding business day.
Value-Added Tax (VAT) presents another critical operational checkpoint. Qualifying vendors registered under Category A or Category B submit bi-monthly VAT201 returns via eFiling by the last business day of the respective month. Every input tax deduction requires an unambiguous, valid tax invoice containing full enterprise legal names, VAT registration numbers, physical business addresses, and a sequential invoice identifier. Disregarding invoice validation protocols during routine supplier payments exposes small enterprises to immediate input tax clawbacks and 10% late-payment surcharges during statutory verification reviews.
Never Miss a South African Statutory Deadline
Receive monthly tax calendar reminders, statutory checklist templates, and regulatory compliance updates directly in your inbox.
Related Enterprise Guides
Continue exploring operational governance and frameworks for South African commerce.