Projection Sheet Specifications
- Operational Domain
- Cash Flow Forecasting & Liquidity Governance
- Document Class
- Structured Spreadsheet Workbook (.xlsx / .csv)
- Statutory Anchor
- Companies Act 71 of 2008 & Tax Administration Act
- Standard Format
- 12-Month Rolling Matrix with Bi-Monthly VAT Rows
- Auditing Cadence
- Weekly Ledger Reconciliations & Monthly Variance Review
- Internal Custodian
- Managing Director / Commercial Accounting Officer
Document Structure & Sections
Establishing Disciplined Working Capital Forecasting
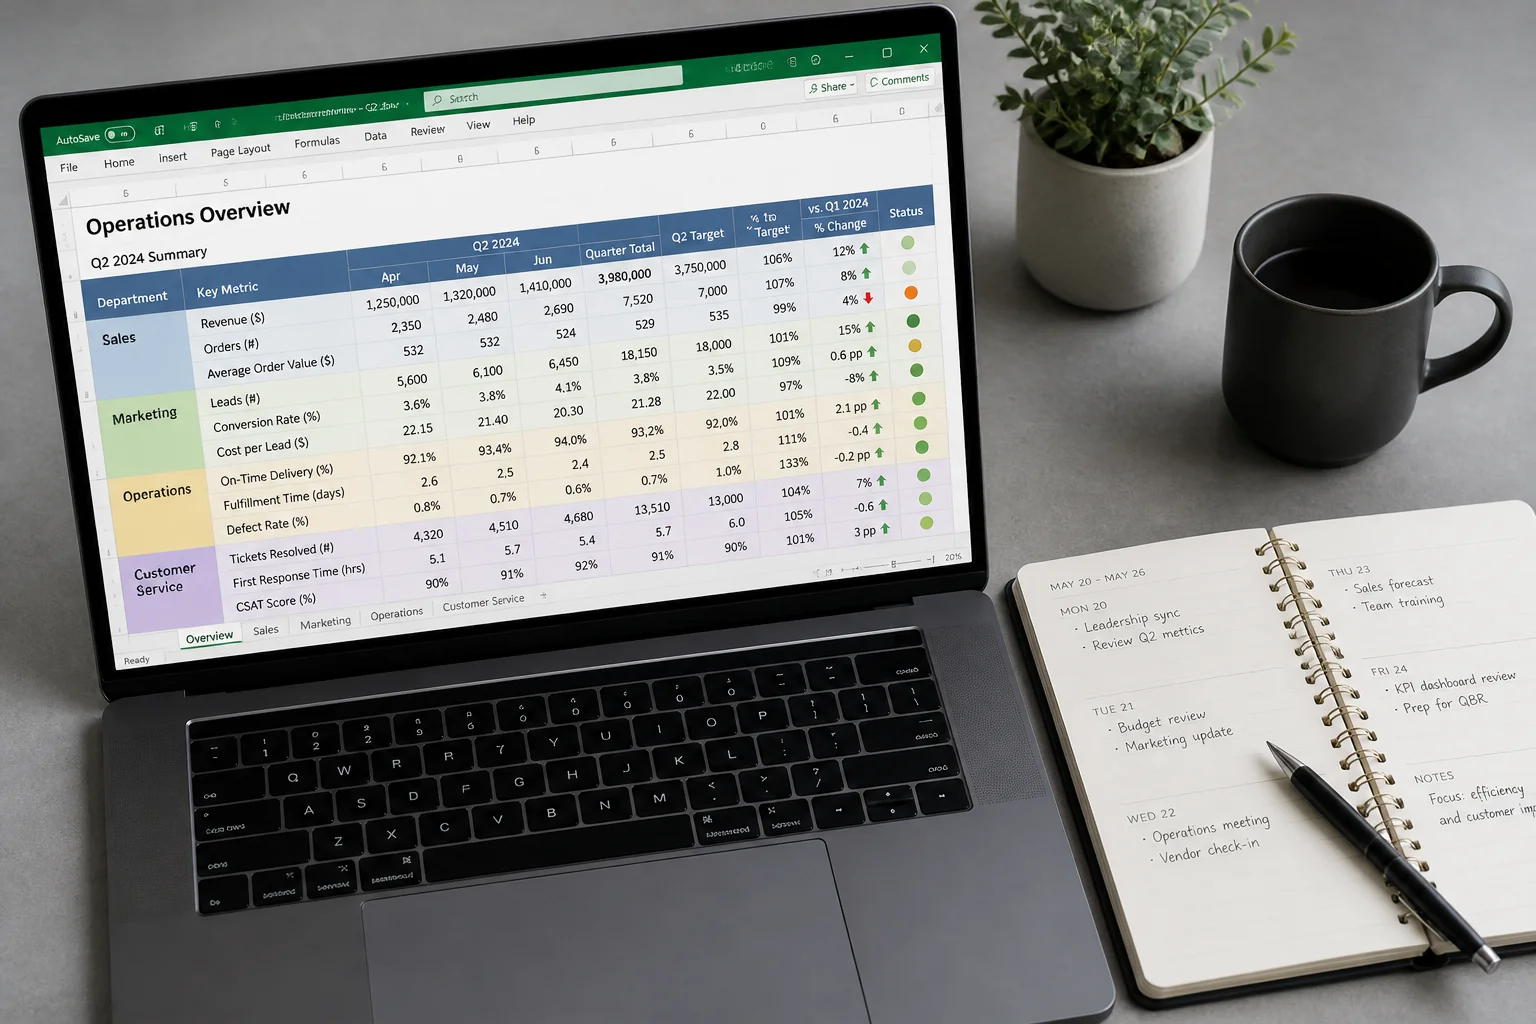
Operational liquidity determines whether a small enterprise survives unexpected economic headwinds, payment delays from corporate clients, or sudden inventory spikes. This projection sheet separates invoiced revenue from realized cash collections, giving operators a truthful vantage point over upcoming bank balances across each trading month.
Unlike standard accounting ledgers that record transactions on an accrual basis, this projection workbook isolates liquid cash entries. Cash receipts from cash sales, debtor settlements on thirty-day terms, and customer deposit retentions appear strictly in the month cash reaches company bank accounts, preventing phantom revenue illusions.
Systematic Three-Stage Maintenance Workflow
Maintaining forecasting integrity demands consistent data entry routines rather than end-of-quarter crisis reviews. Managing directors should delegate sheet updates according to three distinct administrative stages:
- Opening Liquidity Calibration: Reconcile the opening cash position on the first business day of the calendar month against certified business bank statements across all operating accounts.
- Receivables Ageing Attribution: Input confirmed trade debtor receipts by factoring a standard 10% to 15% payment lag into 30-day and 60-day enterprise invoice balances.
- Committed Outflow Allocation: Pre-fill fixed commitments including commercial lease rental, core salaries, utility accounts, and equipment hire before inserting variable inventory replenishments.
Aligning Projections with Statutory Tax Cycles
Under South African tax administration rules, value-added tax vendors must settle bi-monthly VAT liabilities on or before the twenty-fifth day of the succeeding month. This worksheet embeds automated reserve calculations that reserve fourteen percent net VAT allocations into separate ledger rows. By treating statutory tax liabilities as untouchable operational commitments, business leaders prevent year-end cash crises and ensure uninterrupted SARS compliance.
Operational Key Takeaways
- Segregate realized cash payments from accrued invoicing to avoid misleading solvency assumptions.
- Maintain a strict ninety-day cash reserve buffer covering fixed payroll and commercial rent overheads.
- Reconcile projected versus actual bank balances every Friday morning to catch debtor slippage early.
Related Operational Documents